Hail, Wind, and Severe-Weather Repair for Commercial Roofs
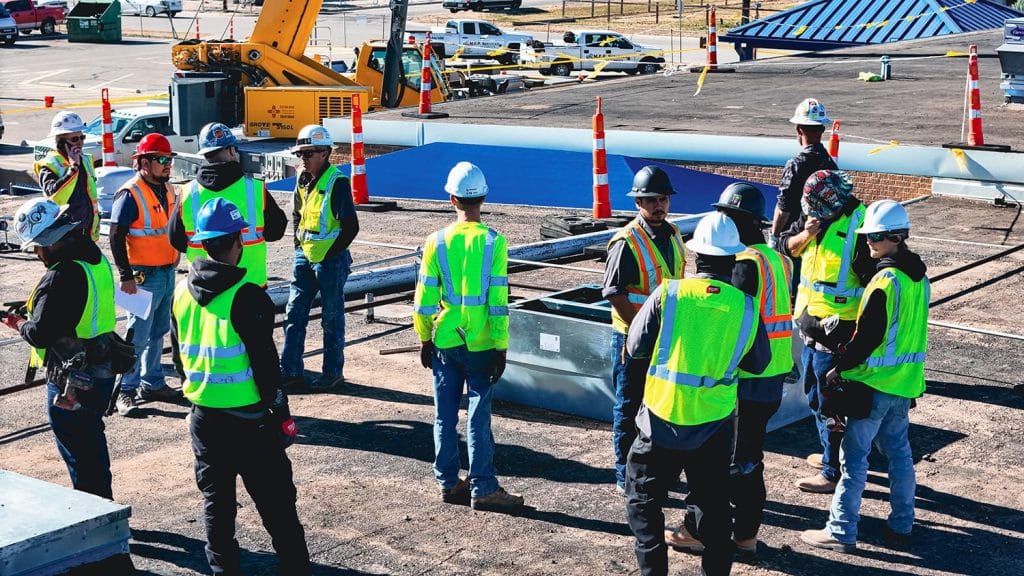
On-site within one business day
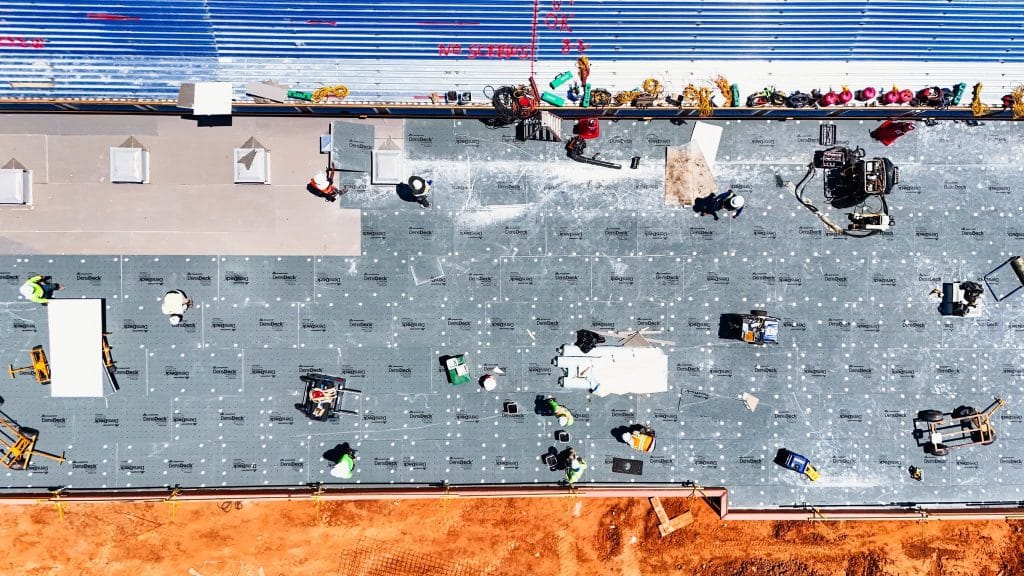
Photos, drone, moisture, written scope
We meet them on the roof
Straight recommendation, no upsell
Storm damage on a commercial roof is not always obvious
Hail on a commercial single-ply membrane rarely tears the sheet in a way you can see from the ground. It fractures the membrane, breaks down granules on modified bitumen, and dents metal panels — and the damage often does not show up as an interior leak for months. By then the insurance clock is running out.
Our commercial storm-damage assessment is built around what actually happens to a commercial roof in a West Texas hail event: we walk the field, core-sample suspect areas, run a moisture scan, and document conditions in the format your insurance carrier needs. If the damage is real and covered, you get a full claim package. If it is not, we tell you that too.
- Hail impact assessment across membrane, coping, and equipment
- Wind uplift, seam separation, and edge-metal damage inspection
- Infrared moisture scan to find hidden saturation
- Drone imagery and geo-tagged photo documentation
- Written scope of damage delivered to your carrier
Storm damage types we handle
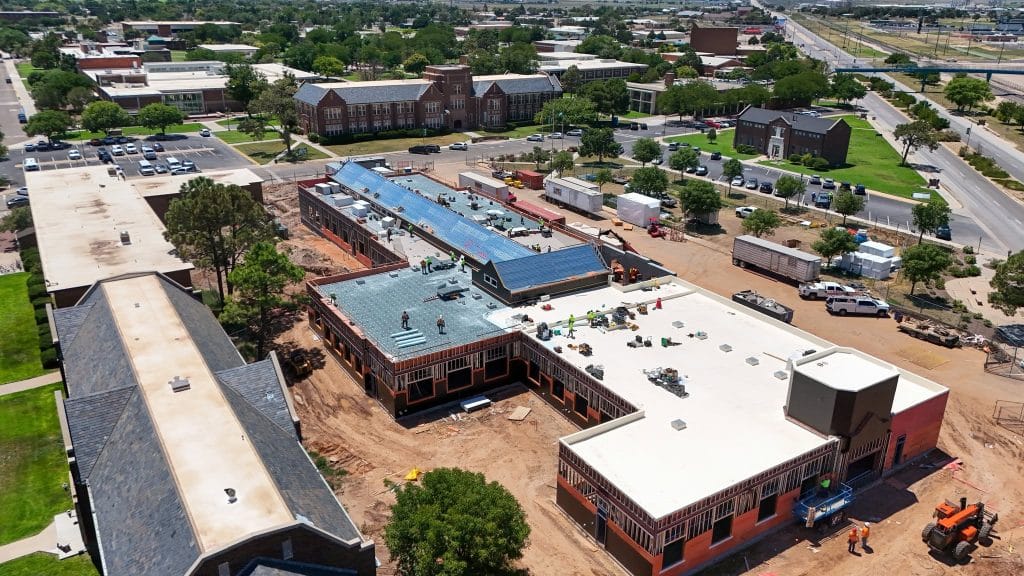
The Llano Estacado and Permian Basin see a specific weather mix. Here is what we most often find on commercial roofs after a severe event.
Hail Impact
Fractured single-ply, cracked coatings, granule loss on modified bitumen, and dented metal. Documented per carrier requirements.
Straight-Line Wind
Membrane billowing, seam separation, edge-metal peel, and coping displacement. Common in 60+ mph events across the South Plains.
Microburst & Uplift
Concentrated wind events that lift ballast, tear fully adhered membranes off the deck, or fail the perimeter attachment.
Debris Impact
Tree limbs, construction debris, and wind-driven objects that puncture the roof or damage penetrations and equipment curbs.
Rooftop Equipment
HVAC units, exhaust hoods, and satellite equipment damaged or dislodged — with secondary damage to the membrane below.
Post-Storm Water Intrusion
Interior damage from a storm-compromised roof, often traced back to a source that is not directly above the damage.
What happens after your call
01. Assessment Scheduled
We come to your building. On-site within one business day for storm-damage assessments across our service area.
02. Documentation
Walk-through, core samples where warranted, drone imagery, moisture survey. Everything the carrier needs.
03. Adjuster Meeting
We meet your insurance adjuster on the roof, walk the scope with them, and coordinate the loss report.
04. Repair or Replace
Straight recommendation: repair, targeted section replacement, or full roof replacement. Written scope and price.
Repair or replace? The honest version
Not every storm claim needs to become a full roof replacement — and any contractor who tells you it does before they have walked your roof is trying to sell you the biggest job, not the right one.
Our assessment tells you what the damage actually is, what the manufacturer’s position on repairability is likely to be, what a targeted repair will cost against a full replacement, and how each option affects your remaining warranty. Then you decide, with the facts in front of you. When the answer really is replacement, we tell you that and handle it. When it is not, we do the repair right and put the roof back into its warranty cycle.
Storm damage FAQs
As soon as reasonably possible. Most commercial policies require prompt loss reporting, and hail damage in particular is often invisible from the ground but easy to document within days. Waiting weeks or months makes both the claim and the repair harder
It depends on the damage, the policy, and the roof's condition before the storm. Our assessment gives you the damage picture; your carrier decides coverage. When we meet your adjuster on the roof, that conversation goes better than a phone call from an office.
Yes. We document the loss, coordinate directly with your carrier, and perform the repair or replacement in-house. Details on the claim-side workflow are on our insurance claim assistance page.
That is a common finding on West Texas commercial roofs — hail simply pushes a marginal system over the edge. Your carrier will factor age and pre-existing condition into the settlement. We give you an honest read on both, and on whether a full replacement makes better long-term sense than a repair.